
In this month’s update, our Chief Investment Officer, Jeff Brummette, reflects on a month in which financial markets demonstrated notable resilience despite ongoing geopolitical tensions and continued uncertainty around inflation, interest rates and global growth. He examines the key themes shaping investor sentiment, highlights developments across equity, fixed income and commodity markets, and outlines how these trends are influencing our investment positioning as we move into June. Looking ahead, Jeff also shares his perspective on the economic and policy factors likely to remain in focus over the coming weeks.
_______
Failure to achieve a peace deal with Iran, and the continued effective closure of the Strait of Hormuz, did little to dent sentiment in global equity markets during May. Major markets posted gains over the month, led by the Nasdaq, where semiconductor stocks continued to deliver substantial share price gains.
Equity Markets
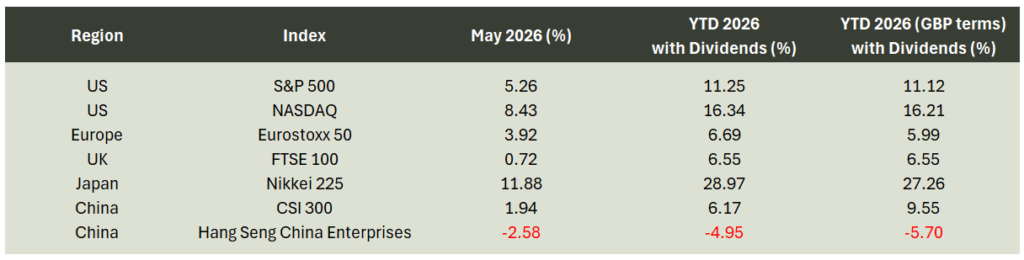
Index returns are in local currency terms except where noted
Source: Bloomberg
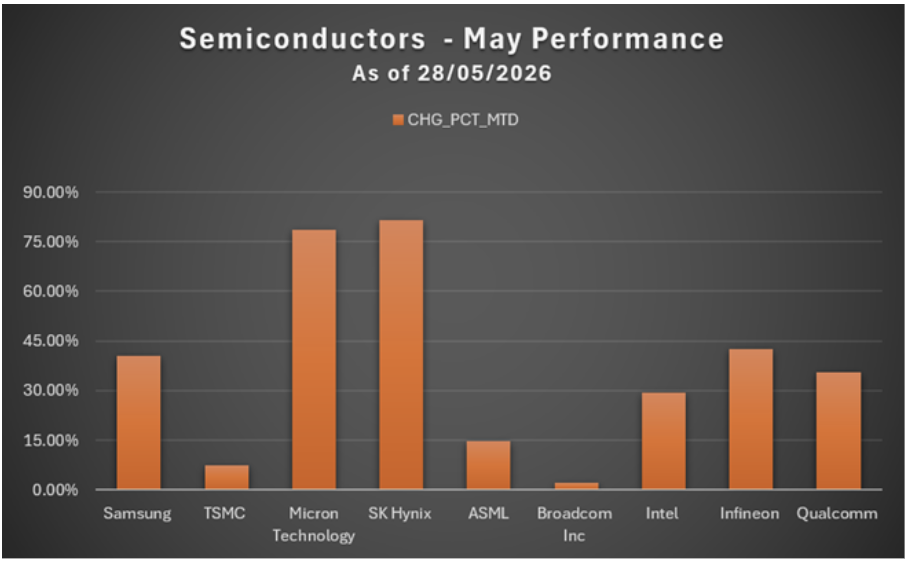
Semiconductor stocks remained the key story in equity markets.
Semiconductors – May Performance
Source: Bloomberg
Nvidia is no longer the only producer (designer) that matters. Computer providers are increasingly recognising that a broader range of chip architectures can enhance, and in some cases substitute for, Nvidia’s GPUs.
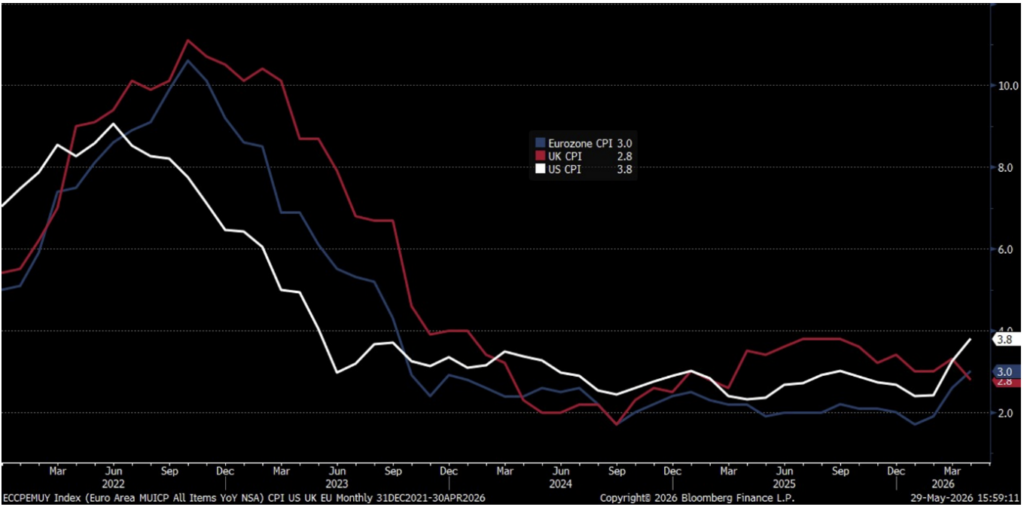
Fixed income markets also produced positive returns, as investors wrestled with the competing pressures of higher inflation and the potential for further central bank rate hikes against the prospect of slower growth driven by high energy prices.
Inflation Levels of UK, U.S. & Eurozone
Source: Bloomberg Finance L.P.
Expectations for rate hikes moderated as UK inflation surprised to the downside in April. In the U.S., Kevin Warsh was sworn in as the new Chair of the Federal Reserve (Fed). His stated preference for lower rates will probably contain a Fed that might otherwise lean more heavily towards tightening. In Europe, mixed messages have been coming from the European Central Bank (ECB), with some policymakers arguing for a hike in June, while others have suggested that now is not the time.
In commodities, gold and silver were both broadly unchanged while copper rose. Bitcoin declined over the month. Currency movements were relatively subdued.
Alternative Investments Markets
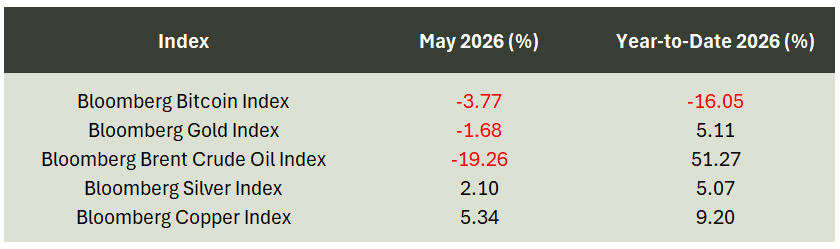
Commodity returns are versus the U.S. dollar
Source: Bloomberg
Currency Rates
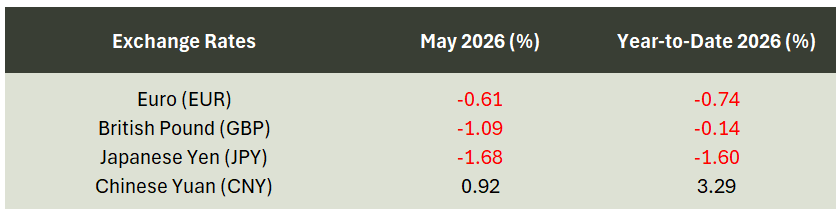
Exchange rate changes are versus the U.S. dollar
Source: Bloomberg
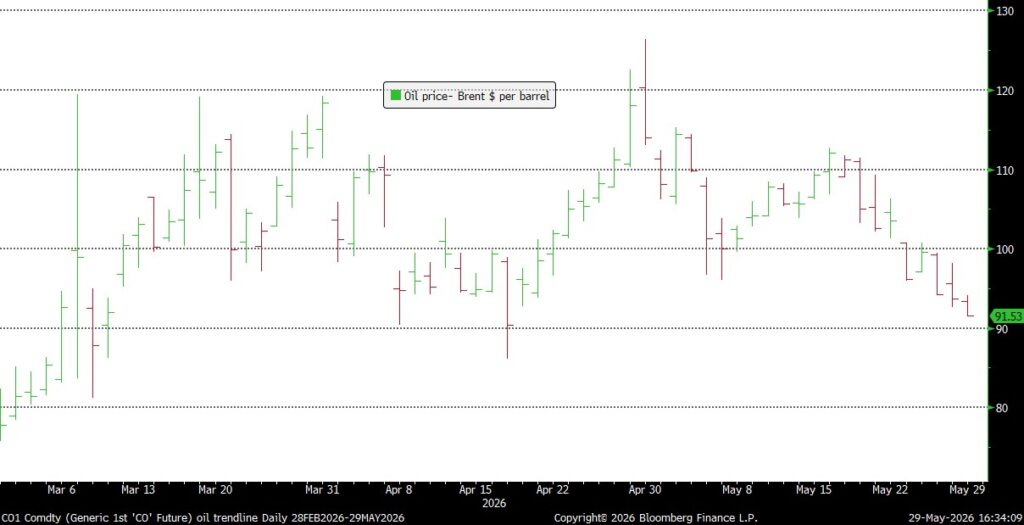
Energy prices remain extremely volatile, reacting to a steady flow of news around the state of peace negotiations between the U.S. and Iran.
Brent Oil Price ($/barrel)
Source: Bloomberg Finance L.P.
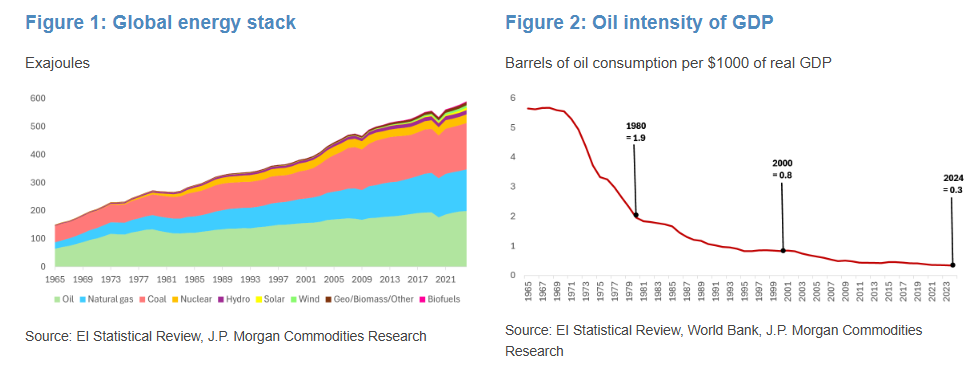
Despite an almost 15 million barrel per day reduction in global oil supply, world growth has yet to show any meaningful signs of slowing. Part of the shortfall is being filled by drawdowns of existing stocks and releases from government petroleum reserves. In addition, some demand destruction is beginning to emerge, as higher prices alter consumer and business behaviour. Consumers are driving less, switching more quickly to electric and hybrid vehicles, and reducing air travel. Shipping operators are also reducing fuel use by running vessels at slower speeds. More broadly, the global economy is less reliant on oil as its primary energy sources than in previous decades.
Global Energy Stack and Oil Intensity of GDP
Source: EI Statistical Review: J.P. Morgan Commodities Research
Our core investment themes of AI, electrification (energy), mining and defence continued to perform well in aggregate. AI has dominated recently, but both mining and defence also delivered positive performance in May after struggling during the early months of the war.
During the course of May we added exposure to the oil sector. It remains difficult to see a resolution to the conflict that would return prices to pre-war levels unless the U.S. completely removes the existing Iranian regime. While President Trump has threatened to resume significant military operations in pursuit of regime change, he has so far chosen not to do so. Rather, negotiations continue, and it seems likely any settlement will leave Iran still capable of threatening shipping through the Strait. Over time, this issue may ease as Gulf energy producers build more pipelines running to the Red Sea, so they can avoid shipping product through the Strait of Hormuz. The U.A.E., for example, has said that a new pipeline to the Red Sea is expected to be operational in 2027.
Looking ahead to June, the major central banks will all meet this month. Despite the continued upward pressure on inflation, we do not expect any of them to raise rates at this stage. Bank of England (BoE) Governor Bailey recently commented that the BoE may be prepared to tolerate inflation remaining above target for a time to manage the downside risks of a weak economy and labour market. In our view, the ECB and the Federal Reserve appear to be taking a similar approach. For now, the start of an extended monetary tightening campaign is not something to worry about (yet).
Fiscal deficits continue to widen as the combination of increased defence spending and higher debt servicing costs place increasing pressure on public finances across most major economies. While this is not a good long-term scenario, there is little sign of any serious efforts to rein in spending. As a result, we do not believe that the current equity bull market is about to be damaged by the prospects of tighter fiscal policy.
The price and value of investments and any income that might accrue may fall as well as rise and is not guaranteed. You may not get back the amount of your original investment.
_______
Hear more from the Oakglen experts
Our investment team continue to provide interesting and informative content to help keep you in the loop on recent global news and market trends. See below for some key highlights from around the world which our investment team have also recently covered:
Read more:
- SpaceX’s $75bn Bet on the Future Faces a Reality Check
William Lamond, Investment Director
- May 2026 Investment Summary
Jeff Brummette, Chief Investment Officer
- Central Bank Update: March 2026 – The Energy Shock Part I
Central Bank Update: May 2026 – The Energy Shock Part II
Jeff Brummette, Chief Investment Officer
You can read other articles from the team on our News & Insights page.
Sign up below to receive similar content directly into your inbox.
Want to become an Oakglen client?
Get in touch with one of our wealth team via the Contact Us page to hear more about our products and services, and how suitable they are for you and your personal circumstances.