
October saw market volatility persist, with investors balancing a fresh set of geopolitical, political and economic uncertainties against a resilient underlying economic backdrop. Shifting expectations for inflation and interest rates, alongside growing scrutiny of investment in artificial intelligence, created a challenging environment across asset classes. In this month’s review, our Chief Investment Officer, Jeff Brummette, considers the key forces shaping market performance, the implications for investors and why, amid continued uncertainty, a disciplined and diversified approach remains essential.
_______
The volatility of the third quarter continued into October, as markets grappled with energy prices rising further, concerns over the scale of AI related capital expenditure, renewed fiscal uncertainty in France and the imminent U.S. midterm elections.
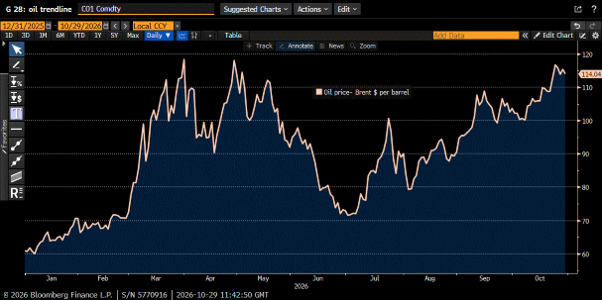
Oil Price ($/Barrell) – Brent Futures
Source: Bloomberg Finance L.P.
Energy markets remained a significant source of volatility. Although the U.S. and Iran have avoided a further major escalation, Houthi attacks on Saudi Arabia damaged infrastructure and contributed to renewed concerns over regional energy supply. Brent crude consequently moved back towards $115 per barrel, close to the highs seen during the earlier phase of the conflict in March and April.
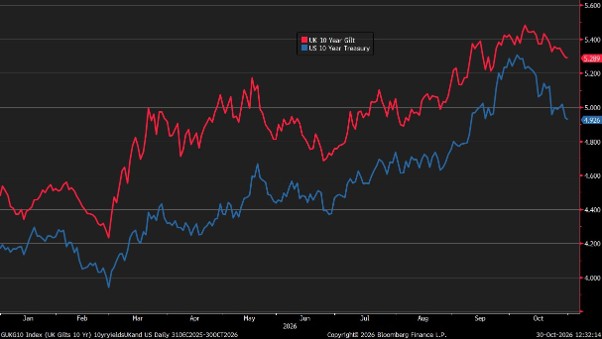
Higher energy prices initially pushed government bond yields higher as investors reassessed the inflation outlook. This coincided with another significant increase in debt issuance from the so-called hyperscalers, the large technology companies that build and operate massive AI data centres. Hyperscaler issuance has been unprecedented and these bonds are becoming an increasingly important component of investment grade bond credit markets. At the same time, persistent government deficits remain a concern for bond markets, with France becoming a particular focus during the month.
Issuance Of U.S. Dollar AI-Related Bonds
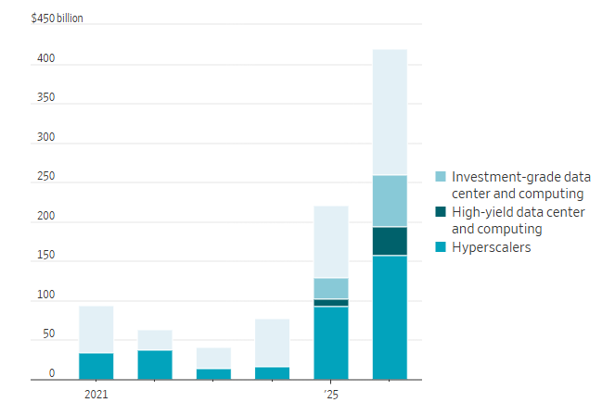
Note: 2026 is through October 16. Issuance is gross figures. Unlabeled bars include other AI-related issuers.
Source: Dealogic, Goldman Sachs Global Investment Research
France’s Economic And Financial Metrics Don’t Look Good
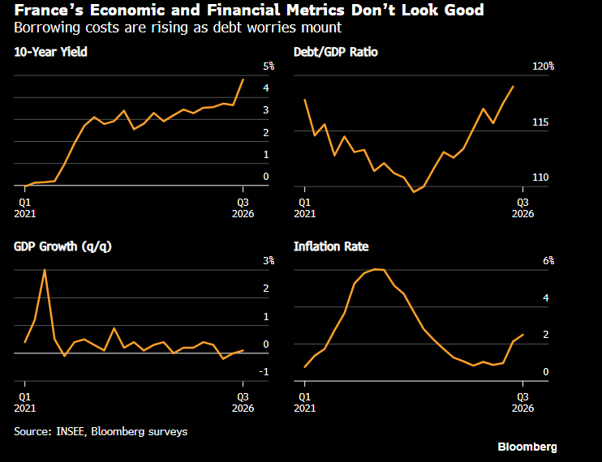
Source: INSEE, Bloomberg Finance L.P.
Ten-Year Government Bond Yield This Year
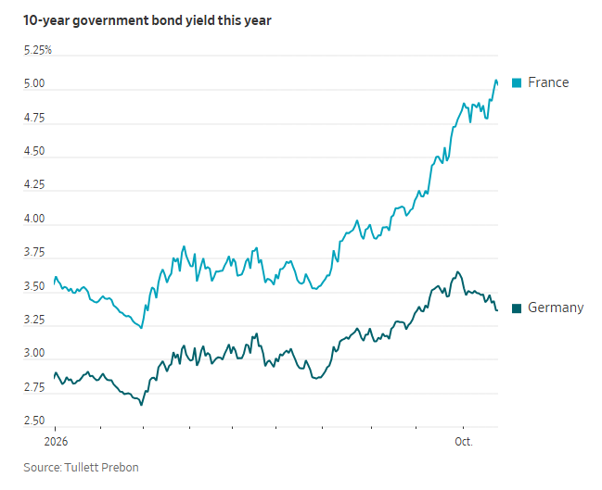
Source: Tullett Prebon
As equity markets weakened later in October, demand for government bonds recovered. Yields subsequently fell by approximately 40 basis points from their intra month highs.
Equity Markets
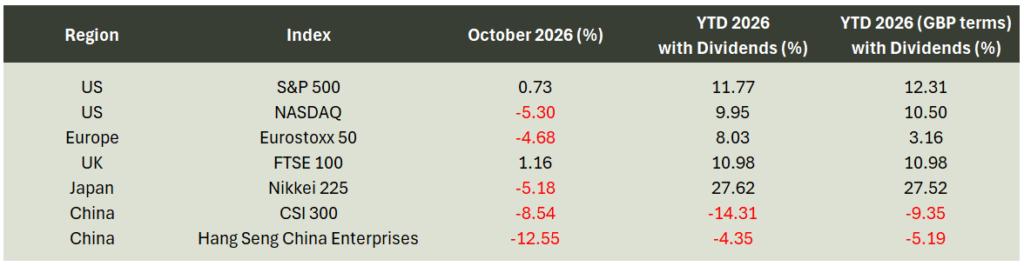
Source: Bloomberg
Fixed Income Markets
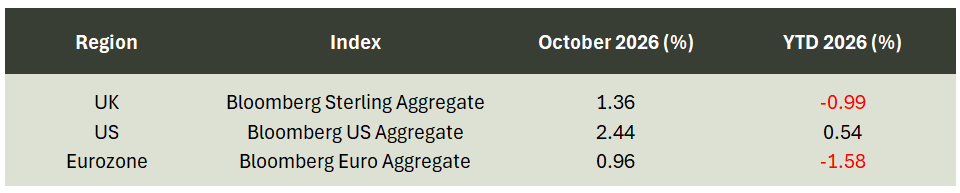
Source: Bloomberg
UK and U.S. Ten-Year Government Bond Yields
Source: Bloomberg Finance L.P.
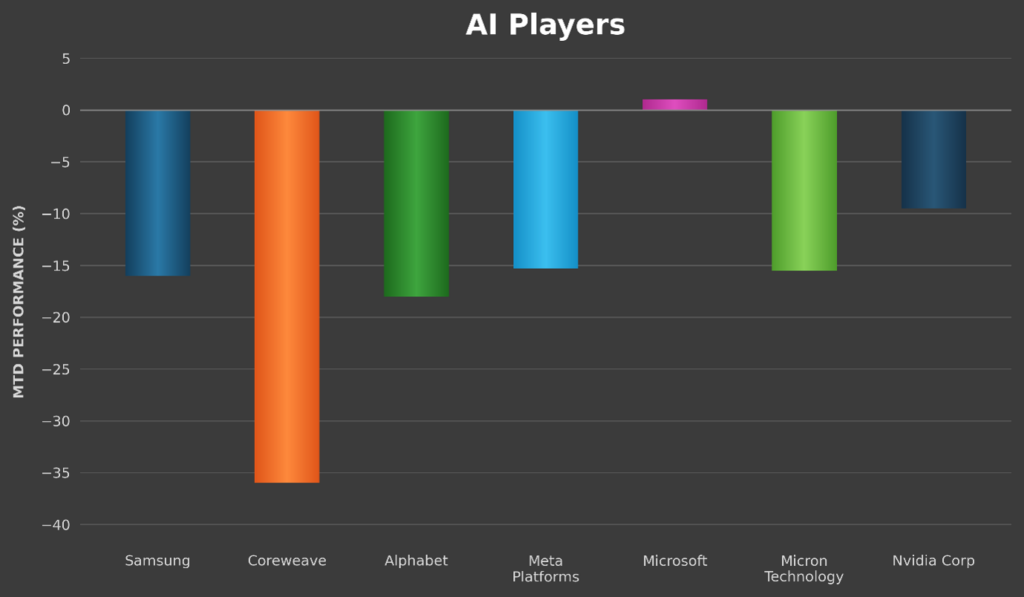
Equity market weakness was concentrated among companies with significant exposure to AI related capital expenditure. Microsoft was a notable exception, performing relatively well as sentiment towards the company strengthened during the month.
October 2026 Monthly % Share Price Change in Major AI Capex Related Companies
Source: Bloomberg Finance L.P.
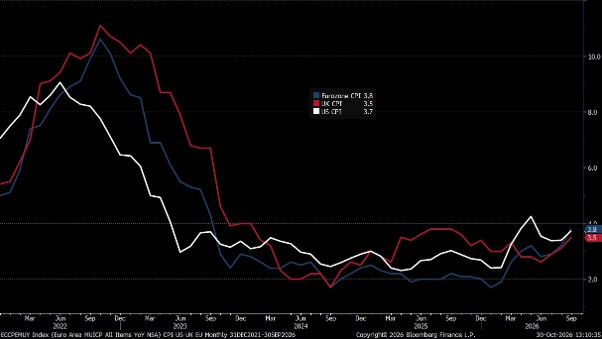
Inflation remains stubbornly above central bank targets, with the recent surge in energy prices adding to near term price pressures. Following the rate increases in September, the major central banks left policy unchanged in October. Both the European Central Bank and the U.S. Federal Reserve emphasised the value of assessing further economic data before making their next move.
Importantly, policymakers also acknowledged that the rise in market interest rates over recent months has itself tightened financial conditions. This reduces some of the immediate pressure on central banks to deliver additional monetary tightening.
Inflation Levels for UK and U.S. & Eurozone
Source: Bloomberg Finance L.P.
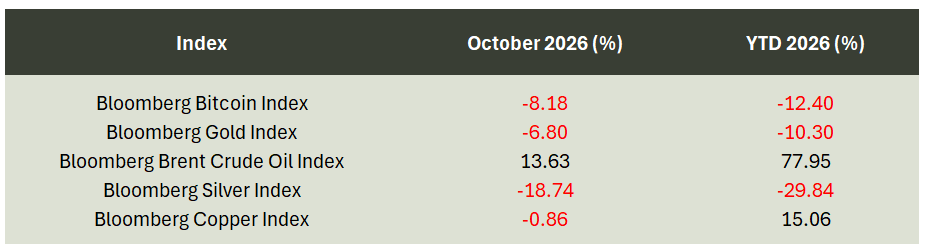
Alternative Investments Markets
Source: Bloomberg
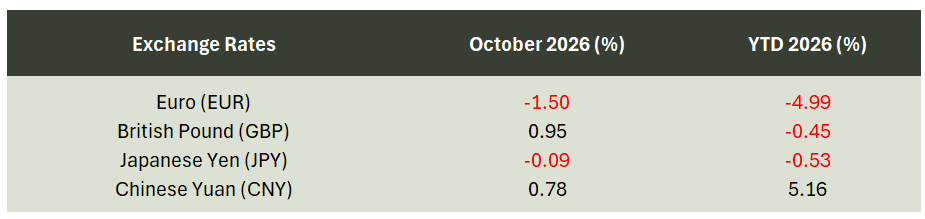
Currency Rates
Source: Bloomberg
Elsewhere, gold and Bitcoin stumbled during the month, while oil and copper advanced. The U.S. dollar delivered mixed performance. Support from relatively tight monetary policy was perhaps offset by concerns over the upcoming midterm elections.
The midterm elections have the potential to become another source of short-term market volatility. Current expectations point towards the Democrats making gains in Congress, which could materially constrain the administration’s legislative agenda. A close or contested result could also generate an extended period of political uncertainty. This may weigh on sentiment towards the U.S. dollar and, potentially, U.S. financial assets more broadly.
Despite these uncertainties, the underlying economic and corporate backdrop remains relatively resilient.
Labour markets remain healthy and, while inflation continues to run above target, central banks are being patient rather than aggressively tightening monetary policy. The U.S. economy recorded GDP growth of 3.4% in the third quarter, while fiscal policy remains supportive.
The outlook for corporate investment also remains strong. The major hyperscalers boosted their expected capital expenditure plans, while semiconductor and GPU manufacturers continue to report strong demand and constrained product availability extending into 2028 and beyond. Corporate earnings growth also remains robust, providing continued support for investment and employment.
Against this backdrop, we believe maintaining a well-diversified portfolio remains particularly important. Periods of market volatility inevitably create areas of weakness, but diversification provides exposure to different sources of return and helps reduce reliance on any single sector or investment theme.
During the recent technology led correction, portfolio exposure to defence, energy and healthcare has provided a useful counterbalance to weakness in AI related and technology holdings.
Our overall assessment therefore remains constructive. Higher energy prices, political uncertainty and elevated investment in AI infrastructure warrant close attention, but they do not, at present, undermine the broader economic or corporate earnings outlook.
The price and value of investments and any income that might accrue may fall as well as rise and is not guaranteed. You may not get back the amount of your original investment.
_______
Hear more from the Oakglen experts
Our investment team continue to provide interesting and informative content to help keep you in the loop on recent global news and market trends. See below for some key highlights from around the world which our investment team have also recently covered:
Read more:
- October 2026 Investment Summary
Jeff Brummette, Chief Investment Officer
- Central Bank Update: September 2026 – Let’s go for a hike!
Jeff Brummette, Chief Investment Officer
- SpaceX’s $75bn Bet on the Future Faces a Reality Check
William Lamond, Investment Director
You can read other articles from the team on our News & Insights page.
Sign up below to receive similar content directly into your inbox.
Want to become an Oakglen client?
Get in touch with one of our wealth team via the Contact Us page to hear more about our products and services, and how suitable they are for you and your personal circumstances.