
The third quarter of 2026 was shaped by a complex mix of geopolitical tension, shifting interest-rate expectations and a notable improvement in the global economic outlook. The renewed conflict involving the U.S., Israel and Iran, disruption to energy markets and rising oil prices all added to inflationary pressures, while stronger economic activity and improving business confidence provided a counterbalance.
Against this backdrop, markets delivered a mixed performance during September, with bonds under particular pressure and equities responding differently across regions and sectors. In this quarter’s investment summary for October, our Chief Investment Officer, Jeff Brummette, considers the forces driving markets, the implications for inflation, interest rates and economic growth, and where we see the most compelling long-term opportunities as the investment landscape continues to evolve.
_______
The third quarter was dominated by three developments.
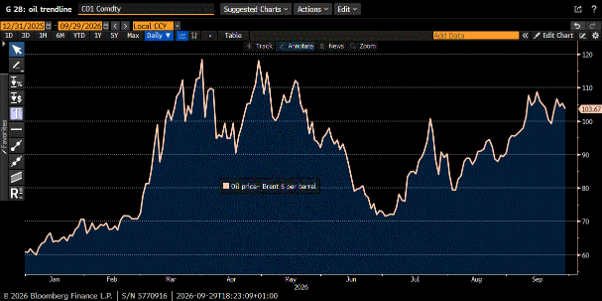
The first was the renewed escalation of the conflict involving the U.S., Israel and Iran following the collapse of the memorandum of understanding in late June. Although the scale of military activity was considerably less intense than the previous three months, disruption to shipping was dramatically impacted as both the U.S. and Iran claimed control over passage through the Strait of Hormuz. In response, oil prices rose back above $100 per barrel towards the end of the quarter.
Oil Price ($/Barrell) – Brent Futures
Source: Bloomberg Finance L.P.
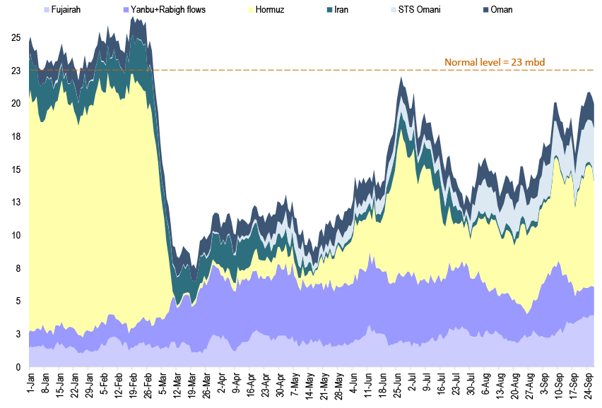
This rise in the oil price occurred despite a recent recovery in the volume of crude oil and refined products passing through the Strait.
Total Oil Flows from the Middle East
Source: Kpler, J.P. Morgan Commodities Research
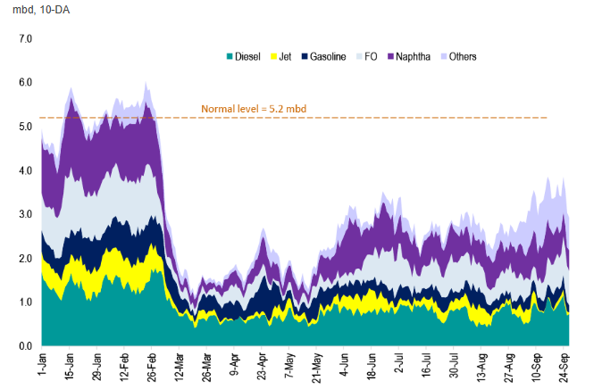
The more immediate risk to economic activity and inflation is the shortage of refined products. Damage to refineries in the Gulf and Russia has constrained global supply, particularly of diesel.
Middle East Refinery Products Flows
Source: Kpler, J.P. Morgan Commodities Research
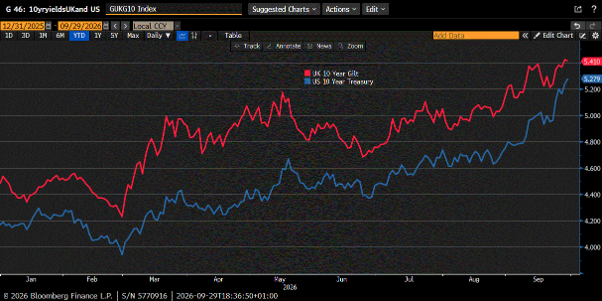
Second, interest rates rose steadily, reflecting higher oil prices, further monetary policy tightening and expectations of additional rate increases. Improving economic growth also contributed to the upward pressure on rates.
UK and U.S. Ten-Year Government Bond Yields
Source: Bloomberg Finance L.P.
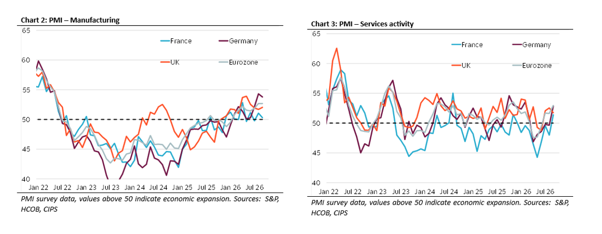
Third, despite higher energy prices, European businesses remain optimistic with purchasing manager surveys pointing to stronger growth prospects.
PMI for Manufacturing and Services Activity
Source(s): S&P, HCOB & CIPS
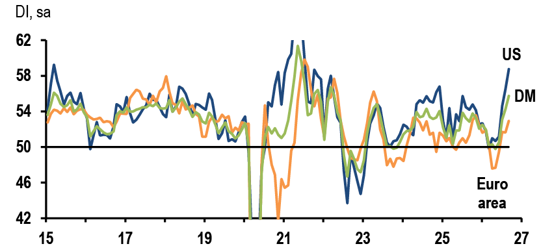
A similar improvement in business confidence is evident in the U.S. and other developed markets.
Services Output PMI
Source(s): S&P Global, J.P. Morgan
Following weaker growth in late 2025 and early 2026, economic activity is now improving.
Year-On-Year % GDP Growth Eurozone, UK and U.S.
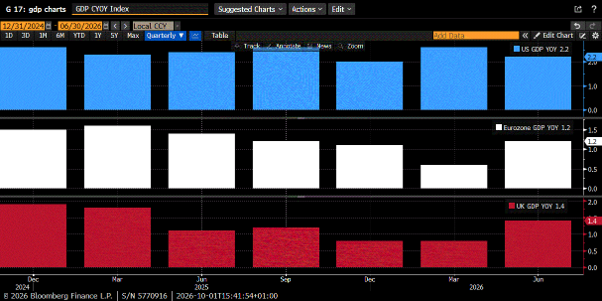
Source: Bloomberg Finance L.P.
Market performance over the month of September and third quarter reflected the interaction of these three developments.
Fixed income markets delivered particularly weak returns in September, extending losses over the quarter and year to date.
Fixed Income Markets
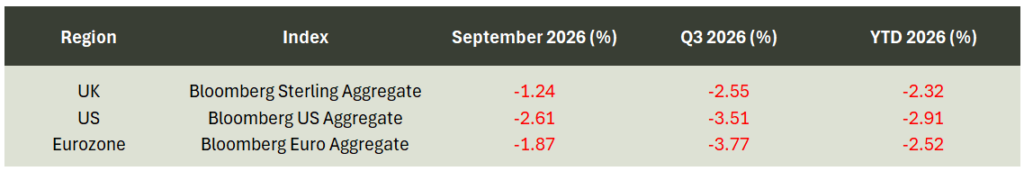
Source: Bloomberg
Equity markets also found it difficult to prosper with the sell-off in fixed income and the change in tone by central banks.
Equity Markets
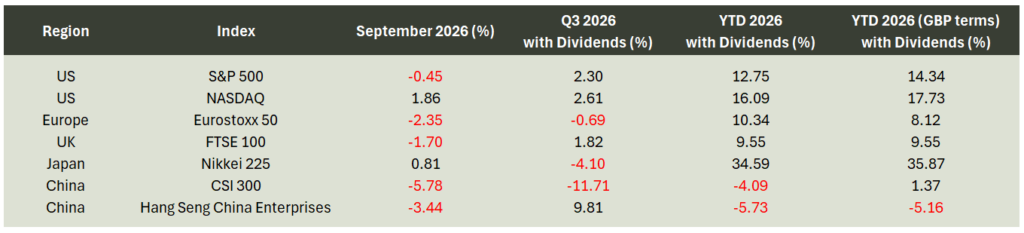
Index returns are in local currency terms except where noted
Source: Bloomberg
Currencies and commodities responded in idiosyncratic behaviour. The U.S. dollar strengthened and gold declined, while Bitcoin and oil rallied. The yen recovered from its lows, with coordinated foreign exchange intervention by the U.S. and Japan having a modest impact.
Alternative Investments Markets
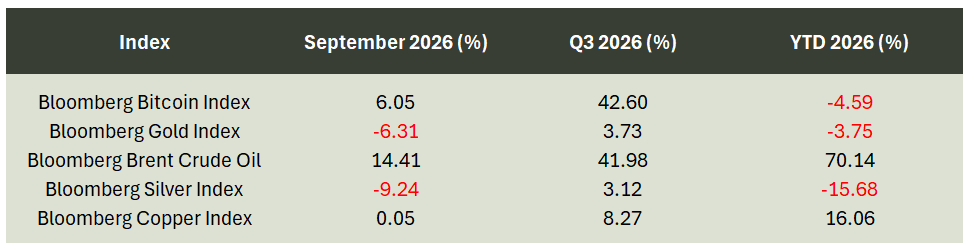
Commodity returns are versus the U.S. dollar
Source: Bloomberg
Currency Rates
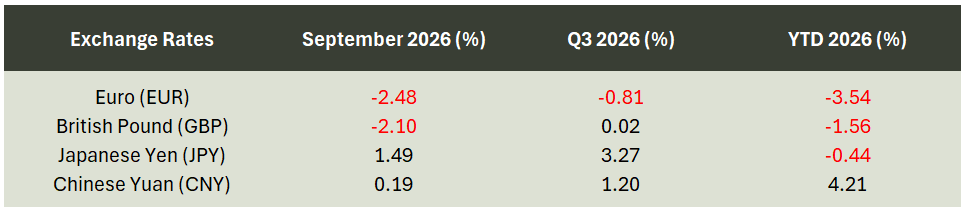
Exchange rate changes are versus the U.S. dollar
Source: Bloomberg
We expect continued upward pressure on yields until there is greater certainty over a resolution to the conflict between the U.S. and Iran. Recent polling points to the Democrats taking the House of Representatives and possibly even the Senate. This may pressure the President to end the war with Iran.
We are less concerned where rising yields reflect stronger economic activity and an improving growth outlook. Robust corporate earnings are very supportive of employment, wage growth and capital expenditure (capex).
Global and U.S. Corporate Profits
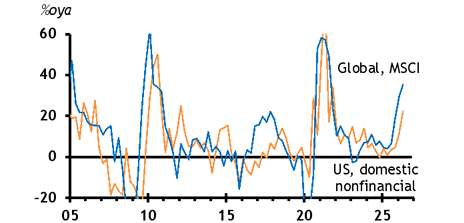
Source(s): BEA, DataStream, IBES MSCI, J.P. Morgan
U.S. Corporate Profits and Private Employment
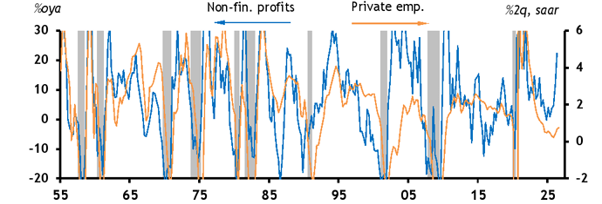
Profit before-tax (IVA, CCA) | Shading denotes U.S. recessions
Source(s): BLS, BEA, J.P. Morgan
Capex related to AI is expected to continue growing as the launch of more advanced models, including Meta’s Muse agent, drives demand for computing capacity alongside rising adoption by households and businesses rises.
Global AI Capex
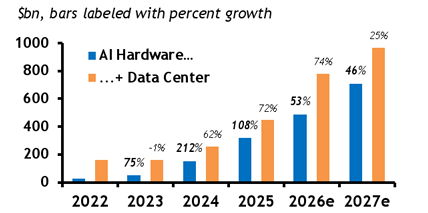
Hardware including silicon and networking; Total adds data centres (real estate, power, cooling, etc).
Source: J.P. Morgan, IDC, and company reports
The combined revenues of the two leading frontier AI model providers OpenAI and Anthropic now exceed $100 billion a year and continue to grow rapidly.
Anthropic & OpenAI Annual Recurring Revenue (ARR) Run Rate
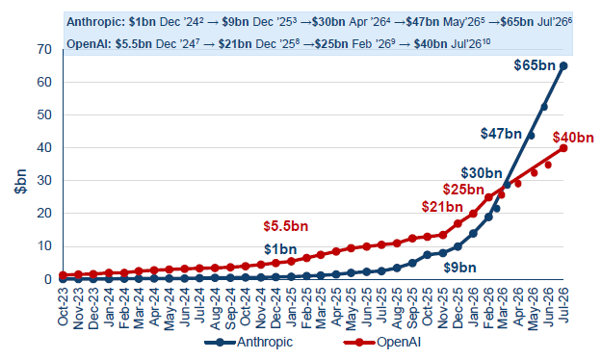
Source: 1. METR, Time Horizon 1.1, 29 January 2026 (P50 doubling 196 days 2019-25 89 days for models since 2024) and METR time-horizons page, updated 8 May 2026. 2. SaaStr, December 2024. 3. Sherwood News, October 2025. 4. Bloomberg March 2026. 5. Anthropic, May 2026. 6. Bloomberg, August 2026. 7. Reuters, October 2025. 8. OpenAI , January 2026. 9. Reuters, March 2026. 10. Bloomberg, August 2026.
Some information contained herein has been obtained from third party sources and has not been independently verified by Oakglen Wealth. Neither Oakglen Wealth nor any other party involved makes any express or implied warranties or representations.
Note: METR defines the time horizon as the length of tasks, measured by human professional completion time that frontier models can complete autonomously with 50% probability.
With inflation seemingly stuck above the widely adopted 2% target, we expect some further monetary policy tightening by the major central banks. However, we view this as a relatively modest adjustment rather than a repeat of the 2021-2023 tightening cycle.
UK, U.S., Eurozone and Japan Policy Rates
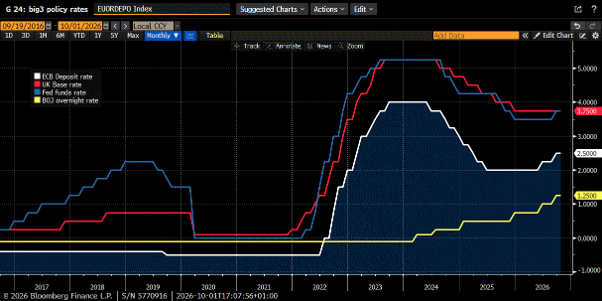
Source: Bloomberg Finance L.P.
We continue to maintain a well-diversified portfolio focused on long term structural themes including technology, defence (including cyber), energy, mining and healthcare. We believe these areas should continue to benefit from rising investment in computing capacity, power generation, national security and the raw materials required to support these developments. Healthcare also provides diversification and exposure to long term innovation. Within fixed income, we remain cautious on longer maturity bonds, which are more sensitive to persistent inflation, higher government borrowing and further increases in yields. We therefore favour shorter to intermediate maturities and higher quality credit, while retaining flexibility should the outlook for inflation and economic growth change. This positioning is intended to capture long term growth opportunities while maintaining resilience in a period of elevated geopolitical and market uncertainty.
The price and value of investments and any income that might accrue may fall as well as rise and is not guaranteed. You may not get back the amount of your original investment.
_______
Hear more from the Oakglen experts
Our investment team continue to provide interesting and informative content to help keep you in the loop on recent global news and market trends. See below for some key highlights from around the world which our investment team have also recently covered:
Read more:
- September 2026 Investment Summary
Jeff Brummette, Chief Investment Officer
- Central Bank Update: September 2026 – Let’s go for a hike!
Jeff Brummette, Chief Investment Officer
- SpaceX’s $75bn Bet on the Future Faces a Reality Check
William Lamond, Investment Director
You can read other articles from the team on our News & Insights page.
Sign up below to receive similar content directly into your inbox.
Want to become an Oakglen client?
Get in touch with one of our wealth team via the Contact Us page to hear more about our products and services, and how suitable they are for you and your personal circumstances.