24.07.25

US Tariffs: Here to stay?

With a major trade deadline fast approaching, tensions are rising across global markets. The U.S. is rapidly finalising new trade agreements, triggering significant market shifts and raising critical questions about the impact on prices, businesses, and consumers. Behind the headlines, legal battles are unfolding that could upend current deals and reshape the trade landscape entirely.

As economic pressures mount globally, the full consequences of this evolving tariff strategy are only beginning to emerge. Read on for a closer look at the latest developments and what they could mean for the future, brought together by our Chief Investment Officer, Jeff Brummette.

_______


The 1st August deadline for trade deals with the U.S. is rapidly approaching. At the time of writing, President Trump has just announced a deal with Japan with tariffs set at 15%. Japan has pledged to open its markets to U.S. rice and other agricultural products and vowed to invest $550 billion into the U.S.

Markets have responded positively to the news, with the Japanese Nikkei 225 Stock Index rallying nearly 4%. It appears that, in the eyes of the market, a certain 15% tariff is preferrable to the 25% tariff Trump recently threatened Japan with. Japanese car manufacturers saw their shares surge on the day, with Toyota Motors up over 14%. Even German carmakers have rallied, as markets extrapolated that the European Union (EU) might secure a similar deal to Japan’s 15% tariff rate.

No one has asked U.S. consumers how they will feel about the prospect of imported car prices increasing by 15%.

The U.S. has also agreed deals with Vietnam at (20%), Indonesia (19%), and the UK (10%). Negotiations are ongoing with China and the EU. The U.S. Treasury Secretary, Scott Besant, has hinted that China may receive a further extension so a deal can be worked out.

Tariffs are already in place on specific commodities; steel and aluminium at 50%, copper set to join them on 1st August. Trump has also hinted at tariffs on pharmaceuticals will be coming. The U.S. imports nearly 40% of the copper it consumes, and domestic copper mines lack the capacity to significantly increase their output. Copper is also used across all industries, so this will inevitable be reflected in prices.

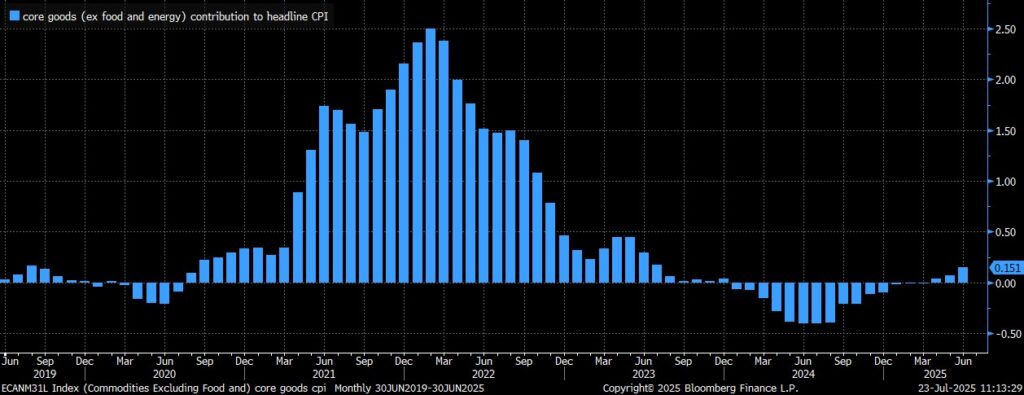
It appears that tariff rates may settle between 15-20%. U.S. businesses and consumers will bear much of this burden. In its latest quarterly report, General Motors cited that tariffs reduced their earnings by 35%. The most recent U.S. inflation data showed goods prices now rising, after a year of goods price deflation.


Core Goods Contribution to Headline CPI Monthly
Bloomberg Finance L.P.


We are only just beginning to see the impact of tariffs on inflation and consumer behaviour in the U.S. Consumers are still unhappy about the overall rise in the price level from the pandemic. They are going to be further aggravated by Trump’s tariffs. The U.S. imports over $3.3 trillion in goods that would be subject to tariffs. At a 15% rate, that equates to $495 billion – an effective tax increase of 1.5% of GDP.

Businesses will also react. U.S. firms have become highly adept at controlling costs. When faced with rising input prices, they are likely to react by raising output prices and/or cutting costs through workforce reductions.

Several significant legal challenges to President Trump’s tariffs remain ongoing. The Court for International Trade vacated Trump’s use of the International Economic Emergency Powers Act (IEEPA) to implement tariffs. Trump appealed and received a stay to that ruling pending an appeal. The appeal will be heard next week in the Federal Circuit Court of Appeals. If this court upholds the original judgement, many of the trade deals may have to be scrapped and tariffs refunded. Trump would likely appeal to the U.S. Supreme Court, although there is no guarantee that the Supreme Court would choose to hear the appeal. There are several similar cases that will be heard this fall.

We are unlikely to have clarity on tariffs for some time.


_______


Hear more from the Oakglen experts

Our investment team continue to provide interesting and informative content to help keep you in the loop on recent global news and market trends. See below for some key highlights from around the world which some of the investment management team have recently covered:


Read more:


You can read other articles from the team on our News & Insights page.

Sign up below to receive similar content directly into your inbox.


Want to become an Oakglen client?

Get in touch with one of our wealth team via the Contact Us page to hear more about our products and services, and how suitable they are for you and your personal circumstances.

Jeff Brummette
Chief Investment Officer

Disclaimer

This document is distributed by Oakglen Wealth Limited and / or Oakglen Wealth (Jersey) Limited (hereafter “Oakglen”) to you for your information and discussion only. Unless otherwise stated nothing in this document constitutes investment, legal, accounting, real estate, conveyancing, surveying or tax advice, or a representation that any investment is suitable or appropriate to your individual circumstances, or otherwise constitutes a personal recommendation to you. It is not a solicitation or an offer to buy or sell any security or other financial instrument. Any information including facts, opinions or quotations, may be condensed or summarised and is expressed as of the date of writing. The information may change without notice and Oakglen is under no obligation to ensure that such updates are brought to your attention. The price and value of investments and any income that might accrue could fall or rise or fluctuate. The price of shares and income from them may fall as well as rise and is not guaranteed. You may not get back the amount of your original investment. A change in the economic environment, possible changes in the law and other events may cause future performance to deviate from that expressed or implied in this document. Please note that past performance, simulations and forecasts are not a reliable guide to future returns. If an investment is denominated in a currency other than your base currency, changes in the rate of exchange may have an adverse effect on value, price or income. Investing in Packaged Retail and Insurance-based Investment Products (PRIIPs) carries a high level of risk and may not be suitable for all investors. Any information provided by a client and used to produce this document will have been checked by Oakglen for plausibility only and the client notified accordingly of any obvious anomalies. This document and any related recommendations or strategies may not be suitable for you; you should ensure that you fully understand the potential risks and rewards and independently determine that it is suitable for you given your objectives, experience, financial resources and any other relevant circumstances. You should consult with such adviser(s) as you consider necessary to assist you in making these determinations. The opportunities and risks associated with each investment product can be found in the relevant underlying securities prospectus and any other supplementary documents. All documents will be made available at any time upon request. Oakglen does not advise on the tax consequences of investments, and you are advised to contact a tax adviser should you have any questions in this regard. The levels and basis of taxation are dependent on individual circumstances and are subject to change. This document may relate to investments or services of an entity/person outside the United Kingdom, or to other matters which are not regulated by the Financial Conduct Authority, or in respect of which the protections of the Financial Services Compensation Scheme. Further details as to where this may be the case are available on request in respect of this document. Additionally, this document may relate to investments or services of an entity/person outside Jersey, or to other matters which are not regulated by the Jersey Financial Services Commission, or in respect of which the protections of the Jersey Financial Services Commission for retail clients. Further details as to where this may be the case are available on request in respect of this document. This document has been prepared from sources Oakglen believes to be reliable, but we do not guarantee its accuracy or completeness and do not accept liability for any loss arising from its use. Oakglen reserves the right to remedy any errors that may be present in this document. Oakglen, its affiliates and / or their employees may have a position or holding, or other material interest or effect transactions in any securities mentioned or options thereon, or other investments related thereto and from time to time may add to or dispose of such investments. This document is intended only for the person to whom it is issued by Oakglen. It may not be reproduced either in whole, or in part, without our written permission. The distribution of this document and the offer and sale of the investment in certain jurisdictions may be forbidden or restricted by law or regulation. This communication does not constitute the solicitation of an offer to purchase or subscribe for any investment or service in any jurisdiction where, or from any person in respect of whom, such a solicitation of an offer is unlawful. Investments may have no public market or only a restricted secondary market. Where a secondary market exists, it is not possible to predict the price at which investments will trade in the market or whether such market will be liquid or illiquid. As such, for investments not listed or traded on any exchange, pricing information may be more difficult to obtain, and the liquidity of the investments may be adversely affected. A holder may be able to realise value prior to an investment’s maturity date only at a price in an available secondary market. The issuer of the investment may have entered into contracts with third parties to create the indicated returns and/or any applicable capital protection (in part or in full). The investment instrument's retention of value is dependent not only on the development of the value of the underlying asset, but also on the creditworthiness of the Issuer and / or Guarantor (as applicable), which may change over the term of the investment instrument. In the event of default by the issuer and/or Guarantor of the investment, and / or any third party the investment any income derived from such contracts is not guaranteed and you may get back none of, or less than, what was originally invested. Parties other than the Issuer or Guarantor (as appropriate) mentioned in this document (for instance the Lead Manager, Co-structurer, Calculation Agent or Paying Agent) do neither guarantee, repayment of the invested capital nor financial return on the investment product, if nothing is indicated to the contrary. Any capital protection given is usually an inherent part of the product; provided through the use of options, futures or other derivative products. You may have to accept smaller returns on an investment relative to a direct investment in the underlying index, basket, etc. because of the costs involved in providing the capital protection. Such capital protection normally only applies if the investment is held until maturity. The amount of initial capital to be repaid may be geared, which means that a fall in the underlying index or securities may result in a larger reduction in the amount repaid to investors. Alternative investments, derivatives or structured products are complex instruments that typically involve a high degree of risk and are intended for sale only to investors who are capable of understanding and assuming the risks involved. Structured products carry counterparty risk, in that in the event of default by the issuer you may lose some or all of your capital invested even when the product carries capital guarantees. Where this document relates to emerging markets, such investments should be made only by sophisticated investors or experienced professionals, who have independent knowledge of the relevant markets, are able to consider and weigh the various risks presented by such investments and have the financial resources necessary to bear the substantial risk of loss of investment in such investments. The services described are provided by Oakglen or by its subsidiaries and/or affiliates in accordance with appropriate local legislation and regulation. Certain products and services may not be available in all locations or to all Oakglen clients. Data Source: Oakglen Wealth (Jersey) Limited and Oakglen Wealth Limited, otherwise specified. Oakglen is a registered business name of Oakglen Wealth (Jersey) Limited and Oakglen Wealth Limited. Oakglen Wealth (Jersey) Limited is regulated in Jersey by the Jersey Financial Services Commission for the conduct of Investment Business and is a limited company with company number 121454, incorporated in Jersey on 7 June 2016. Its business address is 1 IFC, St Helier, Jersey, JE2 3BX. Oakglen Wealth Limited is authorised and regulated by the Financial Conduct Authority. The registered address of Oakglen Wealth Limited is 30 Golden Square, London, United Kingdom, W1F 9LD and is registered in England and Wales with number 13182724.