23.10.25

Q3 2025: Discretionary Investment Management Service Update

It remains as important as ever for us as a business to reflect on our investment performance and the ongoing strategic decision-making process of our team. In this update, Myles Renouf, Senior Investment Manager at Oakglen Wealth, reflects on the third quarter of 2025, set against a backdrop of persistent geopolitical tensions, evolving monetary policy expectations and continued market outperformance.

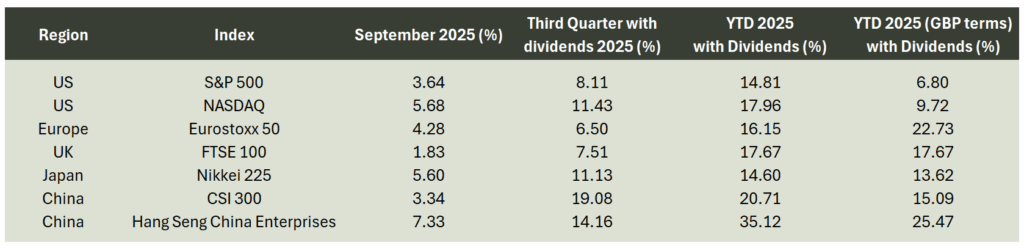
Global equities rallied strongly, with both the S&P 500 and Nasdaq Composite reaching record highs. Small-cap stocks outperformed their large-cap counterparts for the first time in several quarters. This shift was driven by rising expectations of further monetary easing, which tends to benefit smaller companies more due to their heightened sensitivity to borrowing costs and domestic economic trends. As the outlook improved, these firms saw outsized gains.

European equities also advanced in Q3, driven by macroeconomic stabilisation, including 1.2% Eurozone GDP growth, falling inflation and European Central Bank (ECB) rate cuts, which particularly boosted sentiment among the industrial and financial sectors.

In the UK, the Bank of England reduced its base rate to 4.0%. Real wage growth, resilient household balance sheets, and a recovery in discretionary spending contributed to a more constructive outlook. However, the forthcoming Autumn Budget and the potential for increased taxation may cast a shadow over the domestic market in the final quarter of the year.

Chinese equities rebounded strongly in Q3, led by technology and high-end manufacturing stocks. Stimulus measures, easing trade tensions with the U.S., and policy support for domestic chipmakers fuelled the rally.


Equity Markets
Source: Bloomberg


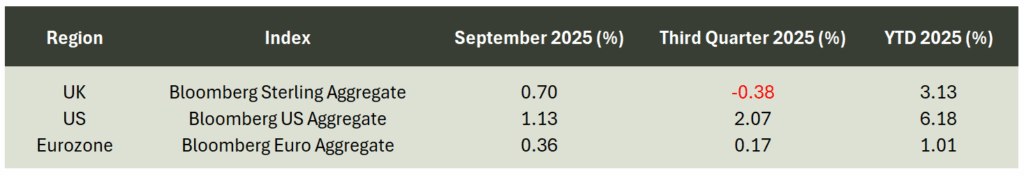
Fixed income markets posted mixed results over the quarter. In the U.S., Treasury prices rose, supported by a Federal Reserve rate cut and narrowing credit spreads. In contrast, UK fixed income underperformed, with the Bloomberg Sterling Aggregate Index delivering a negative return amid persistent concerns over the sustainability of the public sector deficit. European bond markets were more nuanced: shorter-dated maturities benefited from the European Central Bank’s increasingly flexible policy stance, while elevated issuance levels and concerns over fiscal deficits pushed long-term yields higher, steepening the mid-to-long end of the curve.


Fixed Income Markets
Bloomberg Aggregates Total Returns Indices

Source: Bloomberg


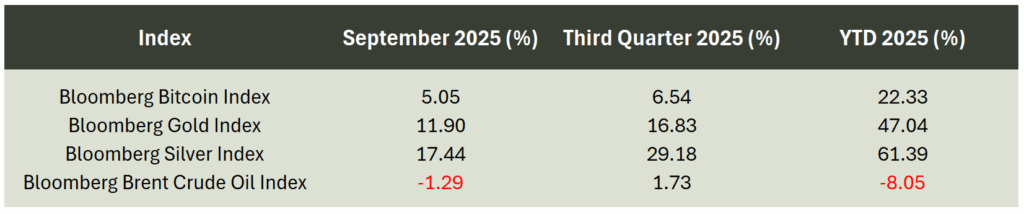
Gold maintained its upward trajectory during the quarter, supported by continued central bank purchases and robust seasonal demand. However, its performance was eclipsed by silver, which rose by over 29%, driven by surging industrial demand – particularly from the solar, electric vehicle, and electronics sectors – tight supply conditions, and strong investor interest, as inflows into silver ETFs reached record highs.


Alternative Investments Markets
Source: Bloomberg


Our discretionary strategies delivered strong relative performance over the course of the third quarter of 2025:

  • Diversify Strategy (medium risk): Delivered a return of +6.28% in Q3 2025, outperforming the ARC Sterling Balanced Asset PCI peer group, which returned +4.04%. Since inception (31 December 2019), the strategy has achieved a total return of +41.34%, significantly ahead of the peer group’s +21.86% return over the same period.
  • Grow Strategy (high risk): Returned +8.66% in Q3 2025, also ahead of the ARC Sterling Equity Risk PCI, which posted a +6.20% return. Since inception, Grow has delivered a cumulative return of +64.53%, comfortably outperforming the peer group’s +34.05%.

Figures refer to past performance. Past performance is not a reliable indicator of future performance. The value of your investment, and any income from it, can fall as well as rise. Your capital is at risk and you may get back less than you have invested.


Key Themes from Our H2 2024 Outlook – Progress in H1 2025

1. Defence Spending

Defence budgets continued to rise sharply in Q3 2025, particularly across Europe, as geopolitical tensions remained elevated. Germany reaffirmed its commitment to reach 3.5% of GDP by 2029, while EU-wide defence spending is projected to hit over €380 billion this year. This sustained fiscal commitment across the continent underpins the long-term growth potential of the defence sector, with our positioning towards European defence firms as a radically aligned core holding within this macro theme.


2. Mega-Cap Tech Resurgence

Mega-cap tech stocks extended their rally in Q3, driven by record-breaking earnings and AI infrastructure demand. Nvidia posted a 94% year-on-year revenue increase, with its data centre segment alone generating over $30 billion. Microsoft, Meta and Broadcom also delivered strong double-digit gains, supported by cloud and AI momentum. The “Magnificent Seven” continued to lead market performance, though elevated valuations prompted more selective positioning among our exposure to broader AI enablers such as networking, storage, optical and hard disc drive as well as expansion into wider AI infrastructure including power and cooling.


3. Foreign Exchange Volatility

FX markets remained volatile in Q3. The U.S. Dollar weakened further, pressured by fiscal concerns, Fed rate cut expectations, and political uncertainty. Sterling held firm, supported by investor rotation out of U.S. dollar assets. The Euro appreciated, buoyed by falling inflation and the ECB’s pause in rate cuts. Diverging central bank trajectories and persistent geopolitical risks continue to drive currency market fluctuations. With volatility likely to persist into Q4, we maintain an underweight position in the U.S. Dollar, anticipating further downside ahead.

4. Economic Policy Divergence

Governments (politicians) remain unwilling or unable to reduce spending, leaving inflation and currency devaluation as the way to deal with their ever-growing debt. Since currencies cannot all devalue at the same time – except against gold (and perhaps silver) – this dynamic appears to be unfolding. While cryptocurrencies may benefit on the margins, central banks and institutional investors will primarily buy gold. The longer maturities of most developed country bond markets are evidencing the same concerns as yield curves steepen around the world. Refinancing existing debt into current levels of interest rates is only increasing the burden of most governments budgets. When this becomes a crisis is not predictable, but it is inevitable without substantial reductions in entitlements in most Western nations. Yet, in the near term, fiscal restraint is absent from policy agendas. We remain positioned at the shorter end of the yield curve, specifically within the 3-to-7-year segment. This area is expected to benefit from potential short-term interest rate reductions, while also helping to mitigate downside risk should inflation reaccelerate and central banks reassess the trajectory of policy rates. At the same time, it continues to offer an attractive yield relative to current rate levels.


To find out more about our discretionary investment management services, please contact the below:


Jersey

 Email Jersey@oakglenwealth.com
  Tel +44 (0) 1534 789 942


UK

 Email  UK@oakglenwealth.com
  Tel  +44 (0) 20 4583 1118


Capital may be at risk.

The price and value of investments and any income that might accrue may fall as well as rise and is not guaranteed. You may not get back the amount of your original investment.

The ARC Private Client Indices are determined by Oakglen Wealth to be the most suitable benchmark for comparison purposes only. It must be noted that the last 3-month performance figures may be based on ARC estimates and may be subject to revision.

Further information can be found here: www.suggestus.com

Myles Renouf
Senior Investment Manager

Disclaimer

This document is distributed by Oakglen Wealth Limited and / or Oakglen Wealth (Jersey) Limited (hereafter “Oakglen”) to you for your information and discussion only. Unless otherwise stated nothing in this document constitutes investment, legal, accounting, real estate, conveyancing, surveying or tax advice, or a representation that any investment is suitable or appropriate to your individual circumstances, or otherwise constitutes a personal recommendation to you. It is not a solicitation or an offer to buy or sell any security or other financial instrument. Any information including facts, opinions or quotations, may be condensed or summarised and is expressed as of the date of writing. The information may change without notice and Oakglen is under no obligation to ensure that such updates are brought to your attention. The price and value of investments and any income that might accrue could fall or rise or fluctuate. The price of shares and income from them may fall as well as rise and is not guaranteed. You may not get back the amount of your original investment. A change in the economic environment, possible changes in the law and other events may cause future performance to deviate from that expressed or implied in this document. Please note that past performance, simulations and forecasts are not a reliable guide to future returns. If an investment is denominated in a currency other than your base currency, changes in the rate of exchange may have an adverse effect on value, price or income. Investing in Packaged Retail and Insurance-based Investment Products (PRIIPs) carries a high level of risk and may not be suitable for all investors. Any information provided by a client and used to produce this document will have been checked by Oakglen for plausibility only and the client notified accordingly of any obvious anomalies. This document and any related recommendations or strategies may not be suitable for you; you should ensure that you fully understand the potential risks and rewards and independently determine that it is suitable for you given your objectives, experience, financial resources and any other relevant circumstances. You should consult with such adviser(s) as you consider necessary to assist you in making these determinations. The opportunities and risks associated with each investment product can be found in the relevant underlying securities prospectus and any other supplementary documents. All documents will be made available at any time upon request. Oakglen does not advise on the tax consequences of investments, and you are advised to contact a tax adviser should you have any questions in this regard. The levels and basis of taxation are dependent on individual circumstances and are subject to change. This document may relate to investments or services of an entity/person outside the United Kingdom, or to other matters which are not regulated by the Financial Conduct Authority, or in respect of which the protections of the Financial Services Compensation Scheme. Further details as to where this may be the case are available on request in respect of this document. Additionally, this document may relate to investments or services of an entity/person outside Jersey, or to other matters which are not regulated by the Jersey Financial Services Commission, or in respect of which the protections of the Jersey Financial Services Commission for retail clients. Further details as to where this may be the case are available on request in respect of this document. This document has been prepared from sources Oakglen believes to be reliable, but we do not guarantee its accuracy or completeness and do not accept liability for any loss arising from its use. Oakglen reserves the right to remedy any errors that may be present in this document. Oakglen, its affiliates and / or their employees may have a position or holding, or other material interest or effect transactions in any securities mentioned or options thereon, or other investments related thereto and from time to time may add to or dispose of such investments. This document is intended only for the person to whom it is issued by Oakglen. It may not be reproduced either in whole, or in part, without our written permission. The distribution of this document and the offer and sale of the investment in certain jurisdictions may be forbidden or restricted by law or regulation. This communication does not constitute the solicitation of an offer to purchase or subscribe for any investment or service in any jurisdiction where, or from any person in respect of whom, such a solicitation of an offer is unlawful. Investments may have no public market or only a restricted secondary market. Where a secondary market exists, it is not possible to predict the price at which investments will trade in the market or whether such market will be liquid or illiquid. As such, for investments not listed or traded on any exchange, pricing information may be more difficult to obtain, and the liquidity of the investments may be adversely affected. A holder may be able to realise value prior to an investment’s maturity date only at a price in an available secondary market. The issuer of the investment may have entered into contracts with third parties to create the indicated returns and/or any applicable capital protection (in part or in full). The investment instrument's retention of value is dependent not only on the development of the value of the underlying asset, but also on the creditworthiness of the Issuer and / or Guarantor (as applicable), which may change over the term of the investment instrument. In the event of default by the issuer and/or Guarantor of the investment, and / or any third party the investment any income derived from such contracts is not guaranteed and you may get back none of, or less than, what was originally invested. Parties other than the Issuer or Guarantor (as appropriate) mentioned in this document (for instance the Lead Manager, Co-structurer, Calculation Agent or Paying Agent) do neither guarantee, repayment of the invested capital nor financial return on the investment product, if nothing is indicated to the contrary. Any capital protection given is usually an inherent part of the product; provided through the use of options, futures or other derivative products. You may have to accept smaller returns on an investment relative to a direct investment in the underlying index, basket, etc. because of the costs involved in providing the capital protection. Such capital protection normally only applies if the investment is held until maturity. The amount of initial capital to be repaid may be geared, which means that a fall in the underlying index or securities may result in a larger reduction in the amount repaid to investors. Alternative investments, derivatives or structured products are complex instruments that typically involve a high degree of risk and are intended for sale only to investors who are capable of understanding and assuming the risks involved. Structured products carry counterparty risk, in that in the event of default by the issuer you may lose some or all of your capital invested even when the product carries capital guarantees. Where this document relates to emerging markets, such investments should be made only by sophisticated investors or experienced professionals, who have independent knowledge of the relevant markets, are able to consider and weigh the various risks presented by such investments and have the financial resources necessary to bear the substantial risk of loss of investment in such investments. The services described are provided by Oakglen or by its subsidiaries and/or affiliates in accordance with appropriate local legislation and regulation. Certain products and services may not be available in all locations or to all Oakglen clients. Data Source: Oakglen Wealth (Jersey) Limited and Oakglen Wealth Limited, otherwise specified. Oakglen is a registered business name of Oakglen Wealth (Jersey) Limited and Oakglen Wealth Limited. Oakglen Wealth (Jersey) Limited is regulated in Jersey by the Jersey Financial Services Commission for the conduct of Investment Business and is a limited company with company number 121454, incorporated in Jersey on 7 June 2016. Its business address is 1 IFC, St Helier, Jersey, JE2 3BX. Oakglen Wealth Limited is authorised and regulated by the Financial Conduct Authority. The registered address of Oakglen Wealth Limited is 30 Golden Square, London, United Kingdom, W1F 9LD and is registered in England and Wales with number 13182724.